Ondas Is Growing Like a Rocket — But Can $457 Million in Backlog Outrun a $163 Million Operating Loss?
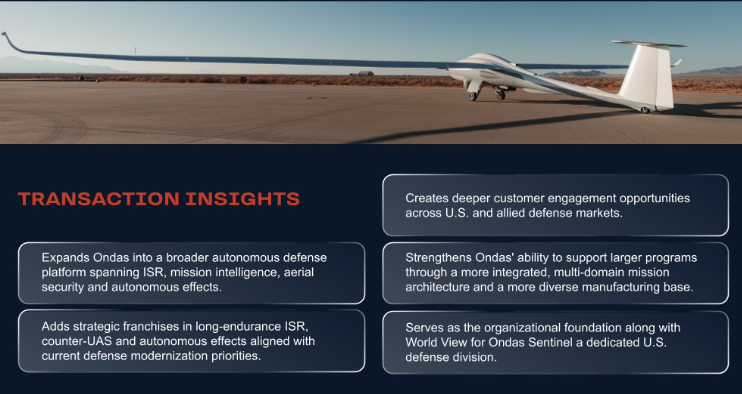
Ondas Inc. is starting to look less like a niche drone company and more like an emerging autonomous-systems platform.
That transformation is exactly why the stock is getting attention.
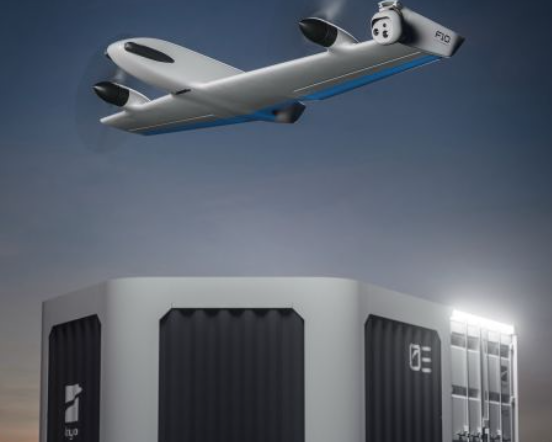
The company now spans aerial drones, ground robots, counter-drone systems, sensing technology, infrastructure inspection, demining equipment and defense applications. Its customer base includes military, homeland-security, public-safety and critical-infrastructure organizations.
On paper, the growth is extraordinary.
Second-quarter 2026 revenue reached $83.8 million, compared with just $6.3 million a year earlier. Gross profit climbed to $36.1 million, while adjusted gross margin reached approximately 50.4%.
Earlier in the year, backlog stood at roughly $457 million, including contributions from acquired businesses. Management also raised its 2026 revenue outlook to at least $390 million.
Those numbers are difficult to ignore.
But neither are the losses.
Operating expenses in the second quarter reached approximately $199 million, producing an operating loss of nearly $163 million.
That contrast may define the Ondas investment story.
The company is growing at the kind of pace investors usually associate with a breakout technology platform. At the same time, it is spending heavily to build that platform, integrate acquisitions and capture market share.
The result is a business with impressive momentum — and equally impressive execution risk.
From Drones to a Broader Robotics Platform
Ondas is positioning itself inside several of the fastest-growing areas of physical AI.
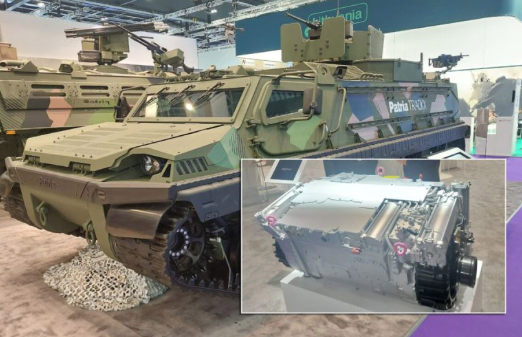
Autonomous aerial systems can perform surveillance, inspection and security missions with reduced human involvement. Ground robots can support defense, logistics and dangerous-field operations. Counter-UAS systems target the rising demand for drone detection and defense.
This matters because the robotics market is moving from demonstrations to deployment.
Investors are no longer looking only at prototypes. Autonomous machines are already entering real operations across defense, logistics, infrastructure and public safety.
That shift favors companies capable of turning technology into deployable systems.
Ondas appears to be trying to do exactly that.
Its opportunity is particularly compelling in defense and security, where autonomous systems are becoming strategically important. Demand for drones, counter-drone technology, robotic ground vehicles and remote sensing is expanding as governments look for systems that can operate in dangerous environments while reducing risk to personnel.
The $457 Million Question
Backlog is perhaps the most compelling part of the story.
A backlog of approximately $457 million suggests meaningful customer demand and future revenue visibility.
But backlog alone does not guarantee profitability.
Orders still need to be delivered. Acquisitions need to be integrated. Products need to perform reliably. Costs must remain under control. And revenue growth eventually has to translate into operating leverage.
That is where Ondas faces its biggest test.
A large portion of the recent operating loss came from acquisition-related costs, stock-based compensation, intangible-asset amortization and other noncash expenses.
Still, cash operating costs remain substantial.
If management successfully integrates its acquisitions and improves efficiency, today’s losses could eventually look like the cost of building scale.
If not, shareholders could face continued losses, further capital raises and potential dilution.
Growth Is Not the Same as Quality
This is an important distinction for investors.
A company can grow very quickly and still destroy shareholder value if that growth requires constant financing or never produces attractive margins.
Ondas therefore should not be judged only on revenue growth.
Investors will need to watch cash consumption, operating expenses, acquisition integration, gross margins, backlog conversion and share issuance.
The technology story is exciting.
The financial story is not yet finished.
Ondas may be building one of the more interesting autonomous-systems platforms in the small-cap market.
But the next phase will determine whether it becomes a durable robotics business — or simply an expensive collection of fast-growing technologies.
The real question is no longer whether Ondas can grow.
It clearly can.
The question is whether it can grow profitably.